New bottom-up opportunities amid the ongoing structural shift, changing economy
Japan’s investment story is evolving beyond corporate governance reform. Economic normalisation, rising wages, increased capital investment and AI-related demand are encouraging companies to transform their businesses and deploy capital more effectively. For investors, this is creating new bottom-up opportunities, particularly among overlooked companies positioned to benefit from structural change.
Structural changes taking place in Japan
For much of the past decade, corporate governance (CG) reform has been one of Japan’s main investment topics. Indeed, reforms in governance, shareholder engagement and capital efficiency have helped improve perceptions of Japan Inc. among investors. While CG reform is an ongoing theme, it is no longer a new story, and investors may ponder where the next opportunities can be found.
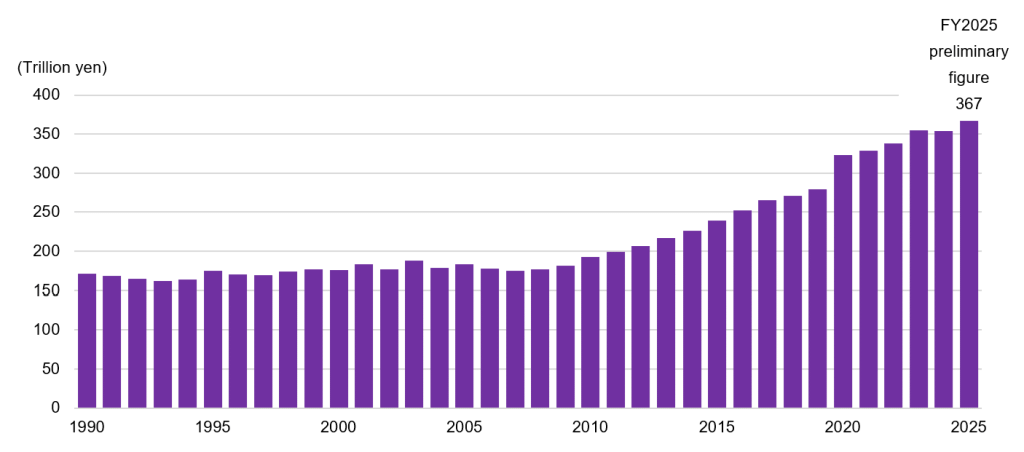
FY2025preliminaryfigure367FY2025preliminaryfigure367FY2025preliminaryfigure367FY2025preliminaryfigure367The answer may lie in a series of structural changes taking place within the Japanese economy. After the so-called “lost decades” characterised by deflation, inflation is back; Japan is finally starting to see signs of a virtuous cycle of stable price increases and rising wages. Interest rates are normalising. Instead of hoarding cash, companies are now more willing to invest. The shift from deflation to inflation may encourage companies to allocate ample capital (Chart 1) more effectively, including through M&As and capital investment, which can improve returns on equity. In addition, Japanese firms are increasingly finding a niche in global artificial intelligence (AI) supply chains. Together, these developments are creating a new set of bottom-up opportunities, particularly among companies undergoing structural transformation.
Chart 1: Cash and deposits of private non-financial corporations (FY1990-2025)
From governance reform to economic transformation
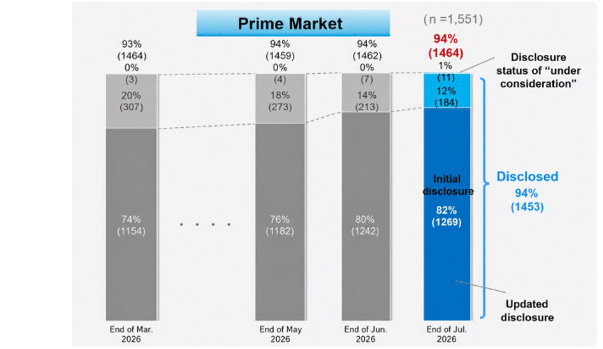
CG reform, initiated more than a decade ago, remains an important foundation of the Japanese market. The Tokyo Stock Exchange (TSE)’s continued push for companies to improve capital efficiency and focus on cost of capital has helped encourage shareholder-friendly behaviour, better disclosure and more disciplined capital allocation. As of the end of July 2026, 1,453 of the 1,551 companies listed on the Prime Market had responded to the TSE’s initiatives and disclosed related information, while a further 11 were considering such a move. All in all, 82% of the listed companies had updated their disclosures at the end of July 2026, up from 74% at end-March (Chart 2).
Chart 2: More companies disclosing information under TSE’s reform initiative
These are encouraging developments, but governance reform alone does not create earnings growth. In our view, what matters going forward is how companies respond to a changing economic environment.
Japan is indeed changing as its economy returns to more normal conditions for the first time in decades. After the bursting of the economic bubble in the early 1990s, Japan struggled with a deflationary period that lasted nearly 30 years. However, inflation has now become entrenched, allowing the Bank of Japan to exit its negative interest rate policy and hike rates. Real wages are rising as labour shortages have now become the norm with many sectors eager to hire more workers. Companies are facing growing pressure to invest, innovate and improve productivity rather than simply accumulate cash.
This transition away from deflation may ultimately prove more important than governance reform itself. For years, many companies thought holding excess cash was prudent. In a reflationary environment, however, idle capital becomes increasingly costly. Companies are therefore being encouraged to deploy their cash holdings. We are starting to see corporate management strategies evolve as firms seek to improve profitability by investing in human capital and fields where they hold a competitive advantage, as well as in innovative R&D and M&As. We believe that the opportunity for investors lies in identifying firms most likely to benefit from adjusting to structural economic changes.
Looking beyond the headline winners
Many international investors continue to focus primarily on Japan’s largest companies. However, some of the most compelling opportunities may be found further down the market-cap spectrum.
One notable feature of our portfolio is its exposure to medium-sized companies that we believe are undergoing meaningful structural change. While large-cap companies remain important holdings, the portfolio has a significantly higher allocation than the benchmark to companies in the US dollar (USD) 3 billion to USD 10 billion market-cap range[1].
These businesses are often overlooked because they have recently faced challenges. Some have struggled with weak demand from China. Others have been affected by cyclical downturns in semiconductors, industrial automation or consumer spending. In many cases, however, the market has focused excessively on near-term problems while underestimating the potential for long-term improvement.
This is particularly relevant to our investment approach, which seeks companies that are suffering from structural issues but possess identifiable catalysts for change. Rather than simply buying cheap stocks, we aim to identify businesses capable of transforming themselves and ultimately improving their earnings profile and market valuation over time.
The next generation of reform beneficiaries
Several examples illustrate how today’s opportunities differ from the first phase of Japan’s reform story.
Toto, the market-leading manufacturer of bathroom fixtures, is a good example of this. Historically, investors viewed the company largely as a domestic housing-related business. Today, the investment case is much broader. Management has been implementing significant restructuring in China while simultaneously benefiting from growing adoption of Washlet toilets in the US. At the same time, the company has developed a semiconductor-related business producing electrostatic chucks used in advanced semiconductor manufacturing. Together, these drivers have the potential to reshape the company’s profit-generating capabilities in the longer term.
At the same time, Sekisui Chemical demonstrates how Japanese companies can benefit from structural themes related to sustainability and energy transition. Its expertise in perovskite solar cells positions it as a potential beneficiary of Japan’s long-term decarbonisation efforts. Unlike traditional silicon-based solar panels, the company’s technology is lightweight, flexible and suitable for installation in places where conventional solutions are difficult to deploy.
Kawasaki Heavy Industries provides another example. While many investors continue to associate the company primarily with traditional heavy industry, we see significant opportunities arising from its position in the hydrogen supply chain and its growing defence-related business. These areas have the potential to drive long-term earnings growth that differs substantially from the company’s historical business mix.
AI creating opportunities beyond software
AI represents another area where the opportunity set in Japan extends beyond the obvious winners.
The global discussion around AI often focuses on model developers and software platforms. However, the physical infrastructure required to support AI may prove equally important. Growing demand for computing power continues to drive substantial investment in semiconductors, data centres, power systems, cables, testing equipment and network infrastructure. Japan occupies a number of critical positions within this ecosystem.
Companies such as Ibiden, Taiyo Yuden and Anritsu have benefited from rising demand linked directly to AI infrastructure spending. Rather than betting on which AI platform ultimately wins, these businesses generate revenues from the supporting infrastructure required across the broader ecosystem.
The concept of “physical AI” may also play to Japan’s traditional strengths. Robotics, factory automation, precision machinery, sensors, motors and industrial components have been areas of Japanese expertise for decades. As AI increasingly expands into manufacturing, automation and real-world applications, many Japanese firms could become core participants in global supply chains.
Conclusion: a different type of opportunity in Japan
The next chapter of Japan’s investment story is therefore unlikely to be defined solely by CG reform. Instead, it may be characterised by how companies respond to a changing economic environment.
Inflation, rising wages, capital investment, AI-related demand and changing corporate behaviour are creating new winners and losers. Importantly, many of the most attractive opportunities may be found not among the obvious market leaders, but among companies that are quietly transforming their business models, improving profitability and repositioning themselves for long-term growth.
For investors willing to look beyond the well-known reform narrative, Japan could continue to offer a significant source of bottom-up opportunities. The challenge today is not deciding whether Japan is changing, as recent developments have shown that the country is in the midst of a structural transformation. Rather, the challenge is identifying the companies best positioned to benefit from what comes next.
[1] Source: Amova Asset Management and JPX Market Innovation & Research, Inc. or affiliates of JPX Market Innovation & Research, Inc. Reference to any particular security or sector is purely for illustrative purposes only and does not constitute a recommendation, nor to be relied upon as financial advice in any way. There can be no assurance that any performance will be achieved in any given market condition or cycle. Past performance or any prediction, projection or forecast is not indicative of future performance.